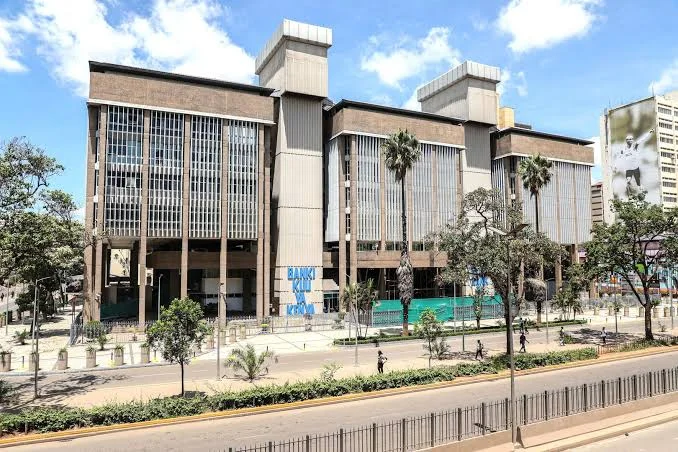
Kenyan lenders are beginning to see relief from the burden of unpaid loans, with non-performing credit declining by Sh41.85 billion as lending activity picks up and repayment conditions improve.
Central Bank of Kenya (CBK) data show that the value of bad loans dropped to Sh646.35 billion, from an estimated Sh688.2 billion, while the share of loans in default also fell over the three months to September 2026.
The improvement signals better loan performance across parts of the economy, even as banks continue to increase financing for businesses and households.
The decline has coincided with lower borrowing costs over the past two years and renewed demand for credit, giving lenders some room to expand their loan books without a corresponding increase in the proportion of unpaid loans.
The CBK reported that the ratio of gross non-performing loans to gross loans fell to 13.9 per cent in September 2026, compared with 14.8 per cent in June. The latest level is also below the 17.6 per cent recorded in August 2025, pointing to a gradual improvement in the banking sector's loan quality.
The decline in defaults was recorded in financial services, agriculture, trade, and energy and water. Improved repayment in these sectors, combined with banks' efforts to recover overdue debts, has contributed to the overall reduction in non-performing credit.
The improvement comes as lenders increase their support for economic activity through fresh loans to companies, traders and individual borrowers. Growing demand for financing has helped lift private sector credit, reversing an earlier period of weak lending.
Gross loans issued by banks rose by 4.3 per cent to Sh4.65 trillion in June 2026, up from Sh4.45 trillion in March. The increase amounted to approximately Sh192.5 billion over the three-month period.
Trade accounted for part of the growth, alongside loans to individuals and households and businesses in the transport and communication sectors. The figures show that the industry's total loan book continued to expand even as the proportion of credit classified as non-performing declined.
Lending momentum has since strengthened further, according to the CBK's latest monetary policy review. Commercial banks' lending to the private sector grew by 10.6 per cent in September, compared with 10.3 per cent in August.
The latest expansion marks a turnaround from the 2.9 per cent contraction recorded in January 2025, when private sector credit was shrinking. The recovery points to improving demand for financing as businesses and households seek funds for their activities and spending needs.
CBK Governor Kamau Thugge said the banking industry remained stable, supported by adequate liquidity and capital, as the non-performing loan ratio continued to fall.
“The banking sector remains stable and resilient, with strong liquidity and capital adequacy ratios. The ratio of gross non-performing loans (NPLs) to gross loans stood at 13.9 per cent in September 2026, down from 14.8 per cent in June 2026, and 17.6 per cent in August 2025,” said CBK Governor Kamau Thugge.
The central bank attributed the growth in credit to stronger demand for loans across trade, building and construction, agriculture, finance and insurance, as well as consumer durables.
The improvement in repayment trends has come against the backdrop of changing interest rates, which have affected the cost of borrowing for both individuals and businesses. Lower financing costs over the past two years have helped ease some of the pressure on borrowers, although the latest figures show that lending rates have not moved down in every comparison period.
Average commercial bank lending rates stood at 14.4 per cent in September, compared with 14.3 per cent in November 2024.
On October 7, the Monetary Policy Committee (MPC), chaired by Thugge, retained the Central Bank Rate at 8.75 per cent. The committee maintained that the existing policy position was suitable for keeping inflation expectations anchored while supporting stability in the foreign exchange market.
The decision was made as inflation edged higher in September. Annual inflation rose to 6.8 per cent from 6.6 per cent in August, although it remained within the central bank's target range.
Core inflation increased to four per cent, while non-core inflation declined to 14 per cent. The CBK expects inflation to remain within its target range in the near term, helped by exchange-rate stability, government interventions and monetary policy measures.
For banks, the fall in bad loans offers a measure of relief after an extended period of high defaults. A lower proportion of non-performing credit can help lenders manage risks while extending more financing to businesses and households.
The figures also suggest that the expansion in lending has not been accompanied by a rise in the overall share of loans going bad. However, the continued level of non-performing credit means banks still need to monitor borrowers closely and ensure that new loans are assessed carefully.
The CBK said lenders continued to make adequate provisions for bad loans, underlining the need to maintain sufficient financial protection against possible losses as lending grows. Careful risk management will remain important as banks extend credit to more customers and sectors of the economy.
Meanwhile, the MPC raised its economic growth forecast for Kenya in 2026 to 5.0 per cent, from the earlier projection of 4.9 per cent. The revised outlook reflects expectations of stronger performance in industry and services.
The combination of declining non-performing loans, stronger private sector credit growth and an improved economic outlook points to better conditions for lenders. However, the central bank's emphasis on adequate provisions shows that banks must remain cautious even as repayment performance improves and demand for loans continues to strengthen.